Monthly cost components
Understand what shapes a monthly cost.
A monthly housing cost is more than a loan payment. Taxes, insurance, dues, utilities, and upkeep belong in the picture, and each is set by a different party. Learn the parts, then take your questions to the people who price them.
Start here
A payment is a stack, not a single figure.
Home comparisons often come down to one line: the loan payment. The monthly cost of owning is wider. It includes what the lender collects, what local governments and insurers charge, what an association or district assesses, and what the home itself needs over time.
Each layer is set by a different party and changes for different reasons. Knowing the layers is the first step toward an estimate you can read with confidence.
The components
What goes into a monthly housing cost.
Each description ends with the question worth asking, and who can answer it.
- Loan principal and interest
- Repays the amount borrowed, with interest, over the life of the loan. Some programs add mortgage insurance. Ask a licensed lender which inputs move this line most, and which of them you can influence.
- Property taxes
- Levied by local taxing authorities and often collected monthly by the lender. Rules differ by state, and a sale or new construction can change the assessed value. Ask a tax professional or the local assessing office how the bill would be estimated for a new owner, not the current one.
- Homeowners insurance
- Lenders require it on a financed home to protect the structure. Premiums follow location, construction, roof age and condition, and claims history. Ask an insurance professional what a policy for this property would cover, what it would exclude, and what drives its cost.
- Wind and flood coverage
- Requirements vary by state and location. A standard homeowners policy does not cover flood, and lenders require flood coverage in certain mapped flood zones. In some coastal areas, windstorm is insured separately or carries its own deductible. Ask an insurance professional what applies at the specific address.
- Special districts and assessments
- Some communities are served by a special district or carry assessments for roads, utilities, or shared facilities. Names and billing differ by state. Ask the district or the community whether any apply, what they pay for, and whether they are expected to change.
- Association dues
- Homeowners and condominium associations charge dues for shared spaces, services, and sometimes insurance on common structures. Ask the association what the dues include, how they have changed, how major repairs are funded, and whether a special assessment is planned. For a condominium, also ask about recent structural inspections and reserve studies, which some states now require.
- Utilities
- Electricity, water, sewer, trash, internet, and sometimes gas or irrigation. Costs follow the size of the home, its envelope, its systems, and the climate. Ask the current owner or the builder for recent utility history, or an energy estimate for a new home.
- Maintenance and repair savings
- Roofs, cooling systems, water heaters, and exterior finishes wear out on their own timelines. Setting money aside each month turns a large future repair into a planned cost. Ask an inspector or builder about the age and expected life of each major system.
Setting matters
Same price, different month.
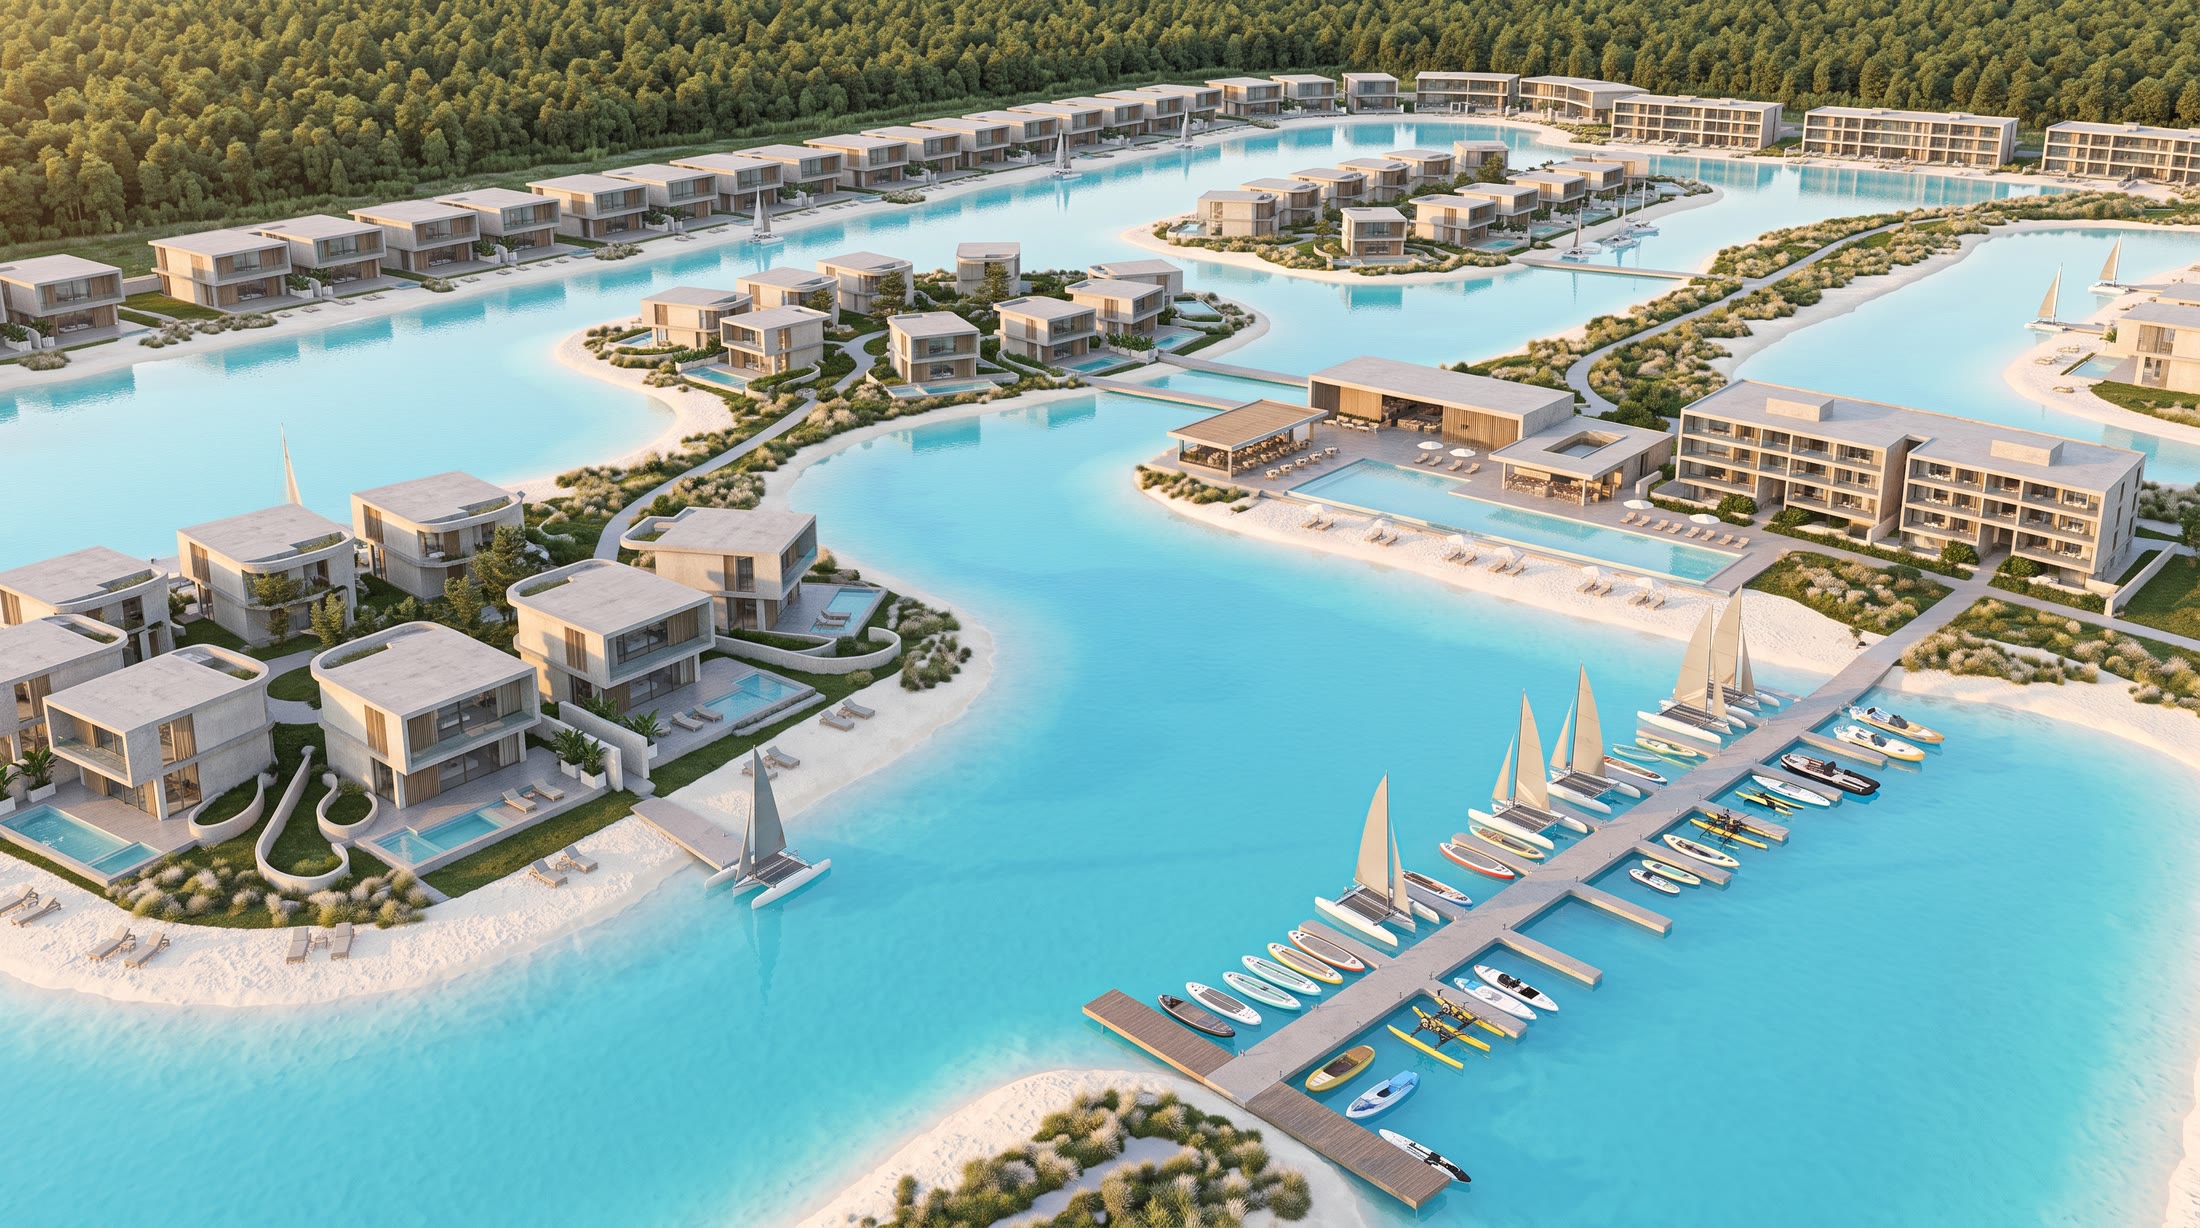
Two homes at the same price can carry very different monthly costs. A home near the water may need flood coverage, and wind coverage there can cost more. A community with a clubhouse, docks, and shared landscape carries association dues, and some communities add district assessments. Compare places by the whole month, not only the price.
Your worksheet
Which of these apply to you?
Check each item that could apply to the home you have in mind. Your selections become a list of questions to take to the people who price each cost. Nothing is calculated, sent, or stored.
Your result
Your questions to bring
Take each question to the party who sets that cost: a licensed lender for the loan, an insurance professional for coverage, a tax professional or the local assessing office for taxes, and the association or district for its charges.
This stays on this page. Nothing is sent or stored.
Reading an estimate
How to read any estimate you are given.
Whether it comes from a lender, a builder, or a spreadsheet of your own, an estimate is only as good as its assumptions.
- 01
Count every layer
An estimate that shows only principal and interest leaves out costs you will pay every month. Look for taxes, insurance, dues, and any district charges.
- 02
Use the specific address
Taxes, insurance, flood zone, and association charges belong to a property, not to an area average. Ask which property an estimate was built on.
- 03
Trace each line to its source
Every line should come from the party that sets it: a lender, an insurer, a taxing authority, an association, or a utility.
- 04
Expect it to move
Taxes, premiums, dues, and some loan payments can change after closing. A plan with some room in it is easier to keep.
Common questions
About estimates and calculators.
Why is there no calculator here?
A useful calculation needs a real price, a loan program, and tax, insurance, and dues figures for a specific property. The communities are in pre-design and none of those figures is set for any home, so a result built on guesses would look more certain than it is. This page teaches the parts instead, so any estimate you receive later is easier to read.
Who can give me a real estimate?
Before you choose a property, a licensed lender can walk through a scenario you describe and show which inputs matter most. An insurance professional can price coverage, a tax professional or the local assessing office can speak to taxes, and an association or district can state its charges. After you apply for a loan on a specific property, the lender issues a Loan Estimate, a standard form that makes offers from different lenders easier to compare, and before closing you receive a Closing Disclosure to check against it.
Why can a monthly payment change after closing?
Lenders often collect taxes and insurance with the loan payment through an escrow account. When a tax bill or a premium changes, the amount collected each month changes too, even if the loan itself does not. Some loans can also adjust over time, so ask a licensed lender how a given loan would behave.
Is a home that is not built yet estimated differently?
Often, yes. Property taxes can be assessed differently during construction and after completion, and insurance is written for the finished structure. Financing depends on whether the home is complete when you close or is paid for in stages while it is built. The financing page explains that difference.
Important
No calculator and no figures, by design.
This page is general education. It does not calculate or display any payment, rate, or cost, and it is not a loan estimate or financial, tax, or insurance advice. Costs for a specific property come only from the lender, insurer, taxing authority, association, or provider that sets them.
Next step
See how financing decisions are made.
Follow the steps from estimate to final approval, see who handles each one, and build a list of questions for a licensed lender.